Responding to SARS Correspondence: Verifications, Audits and Assessments Explained
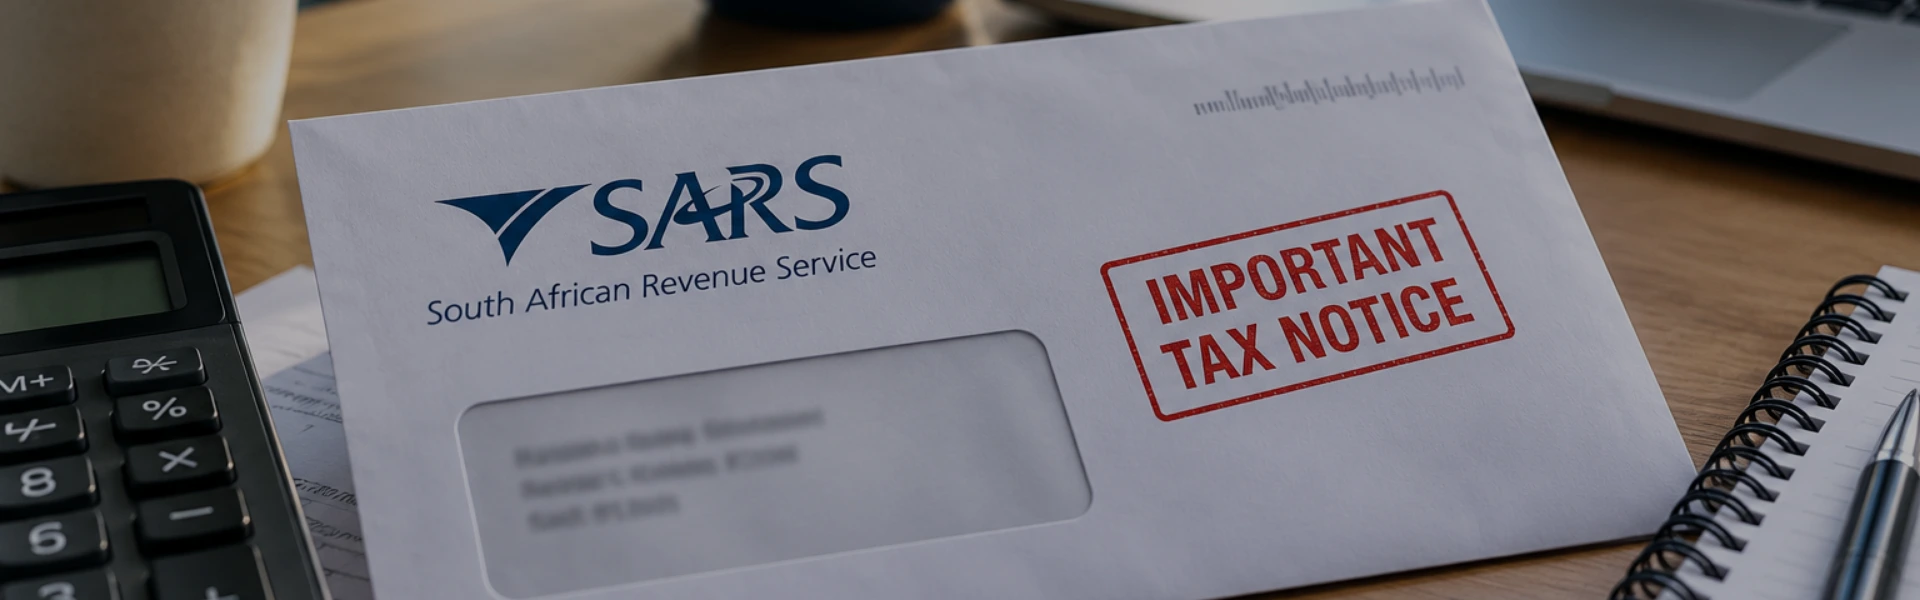
Correspondence from SARS calls for an orderly and timely response. It tends to arrive at inconvenient moments, such as month-end, a busy season or a period of leave, and it is easy to set aside for later. That is an expensive habit for any business or trust. Each SARS request carries a deadline, and a missed deadline can result in estimated assessments, penalties and interest that exceed the cost of replying. When a response is prepared early and in good order, most queries are resolved without difficulty.
Key Facts at a Glance
- SARS’s position: SARS has a revenue target of more than R2.12 trillion for 2026/27. It has stated that it will promote voluntary compliance while making it costly for taxpayers who knowingly fail to comply, including those who miss deadlines.
- Penalties for late returns: automatic administrative penalties may be imposed, ranging from R250 to R16 000 per return per month, depending on assessed taxable income.
- Request for reasons: a taxpayer may ask SARS for reasons for an assessment within 30 business days of the assessment date.
- Notice of objection: due within 80 business days of receiving SARS’s reasons, or of the assessment date where no reasons were requested.
- SARS’s decision: SARS has 60 business days from receiving the objection to decide it, and may extend this period by up to a further 45 business days.
- Notice of appeal: due within 30 business days of the notice disallowing the objection.
- Business days: the dispute rules count business days only, so weekends and public holidays are excluded.
Why SARS Correspondence Requires Attention
SARS has been clear about its direction. It wants more data, earlier visibility and fewer areas of non-compliance. A revenue target above R2.12 trillion places pressure on collection, and that pressure is reflected in more verifications, more requests for supporting documents and less tolerance for unanswered correspondence.
For a business, a letter from SARS is no longer unusual. Companies, partnerships and trusts that keep accurate records and respond promptly usually pass through verification with little disruption. Those that do not respond leave the initiative with SARS.
Identifying the Type of Letter
Not every letter from SARS has the same purpose, and the first task is to establish what has been received. The three most common types are:
- A verification request. SARS selects a return for checking and asks for supporting documents. A verification is generally narrower and quicker than an audit.
- An audit. SARS examines the taxpayer’s affairs in greater depth, often over several periods and several tax types. A wide range of records may be requested, and the process can continue for months.
- An assessment or penalty notice. SARS records its decision. The taxpayer’s dispute rights, and their deadlines, apply from this point.
SARS may also issue a request for relevant material. This is a formal request for any information, document or thing that is foreseeably relevant to its tax risk assessment of the taxpayer. Each letter should be read carefully, as it states the deadline and the documents required.
The Consequences of Not Responding
Silence does not suspend the process. SARS may proceed on the information it already holds, which can include raising an assessment based on its own estimates. Penalties and interest may continue to accrue, and a missed objection or appeal deadline can remove the right to dispute the outcome. A matter that could have been settled with a single set of documents may become a debt, and in some cases a collection matter.
For directors and trustees, the consequences are personal as well as corporate. Trustees remain responsible for the tax compliance of the trust, and a record of unanswered correspondence tends to attract closer scrutiny of other matters.
A Checklist for Responding
- Record the date of the letter and the deadline. Enter the deadline in your diary and in your adviser’s, and treat it as fixed.
- Establish the type of letter. Verifications, audits, requests for relevant material and assessments each follow a different procedure.
- Provide the documents requested, and only those. Submit complete and well-organised records that answer the question asked. Providing additional material can widen the enquiry.
- Request an extension before the deadline expires. If more time is needed, apply in writing and give reasons while the period is still running.
- Respond through the channel and in the format SARS requires. Retain proof of submission.
- Verify the figures before replying. If an error has been made by SARS or by you, it is better identified before submission.
- Consult your adviser early. A brief discussion before responding often prevents a lengthy dispute.
Disputing an Assessment
The taxpayer’s rights are clear, and they follow a strict timetable. A request for reasons must be made within 30 business days. A notice of objection must then be lodged within 80 business days of receiving those reasons or, if none were requested, of the assessment date. SARS has 60 business days to decide, and may extend that by up to 45 business days. Where the objection is disallowed, a notice of appeal may be lodged within 30 business days of the disallowance.
Beyond that stage, alternative dispute resolution may be available, and an application is made within 30 days of the date of the relevant decision letter. Where a taxpayer believes SARS has not followed proper administrative process, the Office of the Tax Ombud may review the complaint. None of these routes can be used once a deadline has passed, which is why the first response is the most important.
How We Assist
Order in business includes an orderly response to SARS. Our team deals with verifications, audits, disputes and tax debt arrangements as part of the taxation and advisory services we provide to businesses and trusts. We review the letter, establish what SARS requires, prepare the response and monitor the deadlines. Sound accounting records, kept current throughout the year, make every later request easier to answer.
Compliance matters often arise together. A SARS query may coincide with other filings that need attention, such as beneficial ownership declarations that can prevent an annual return from being filed, or a trust return that now includes a beneficial ownership declaration. We consider the whole position, not only the letter received. Clients in Modimolle and the wider region can contact our team of professionals at any stage of the process.
Frequently Asked Questions
Q: What should be done first on receiving a letter from SARS?
A: Read the letter in full, note the deadline and establish whether it is a verification, an audit, a request for relevant material or an assessment. Consult your tax adviser before responding, and do not leave the letter unanswered.
Q: How long does a taxpayer have to object to a SARS assessment?
A: A notice of objection is due within 80 business days of receiving SARS’s reasons for the assessment, or of the assessment date if reasons were not requested. Reasons must be requested within 30 business days of the assessment date.
Q: What happens if a SARS deadline is missed?
A: SARS may proceed without the taxpayer’s input, including by issuing an assessment based on its own estimates, and penalties and interest may accrue. A missed objection or appeal deadline can limit the right to dispute the outcome, so a response or a request for an extension should be made before the deadline passes.
A letter from SARS carries a deadline, and the best time to respond is on the day it is received. If your business or trust has received a verification request, an audit notice or an assessment with which you disagree, get in touch with WV Rekenmeesters and let us bring the matter into order before the deadline arrives.